Business History
Explain how long you've operated and whether this is an existing hospice, a new branch, or a startup. A new entity shouldn't be presented as having its owner's operating history.
A new patient may need a bed tonight, while your next reimbursement is still weeks away. Hospice care equipment financing and leasing can spread the cost of beds, mobility aids, delivery vehicles, and supporting systems. If you're considering small business loans, first separate what you need to own from what your DME supplier already provides, then work out what your cash flow can comfortably support.
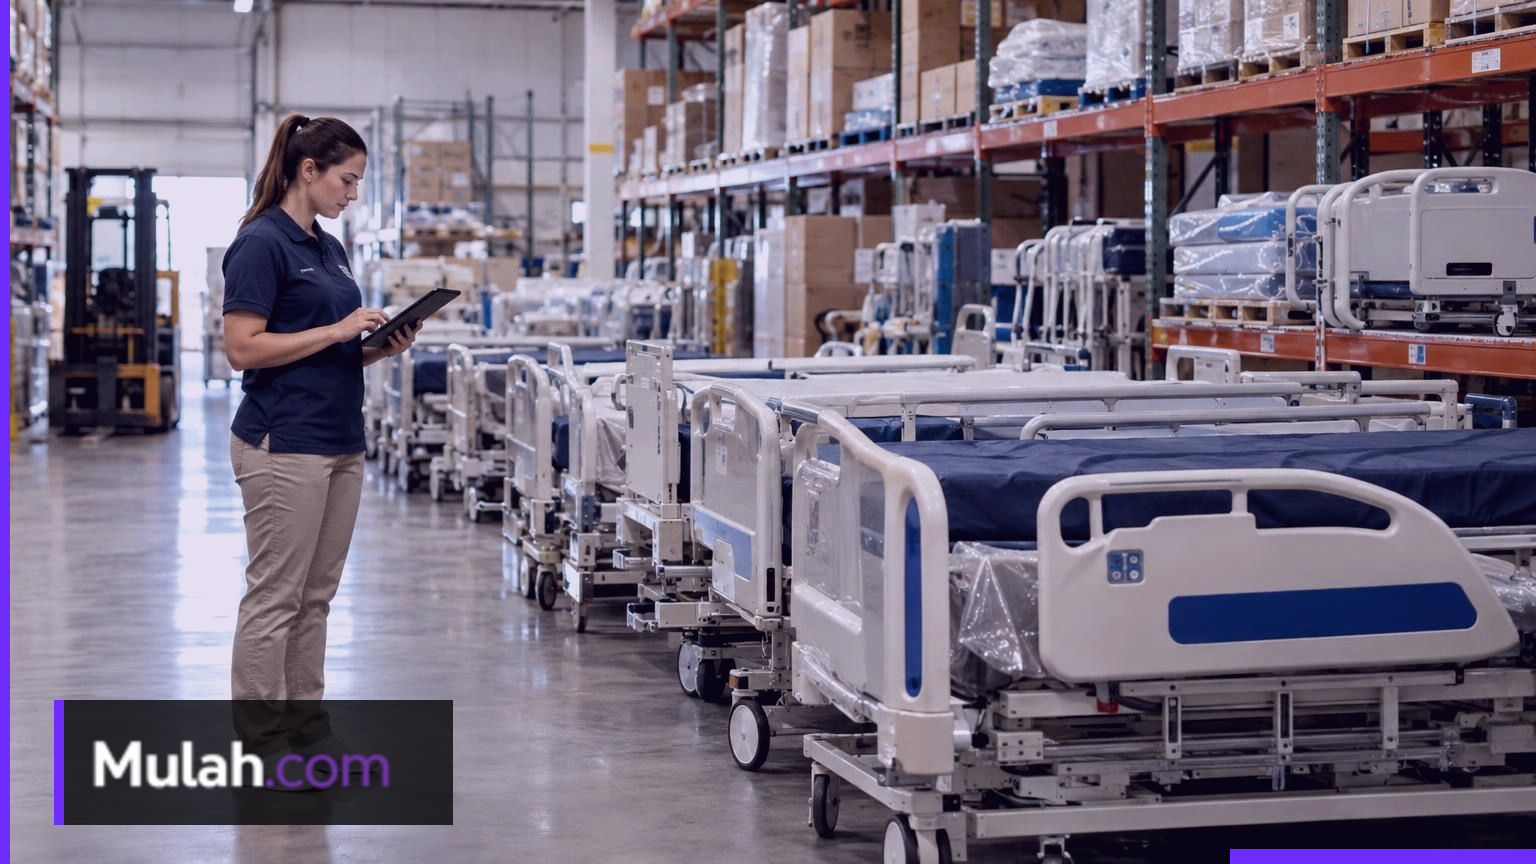
An equipment shortage isn't always a purchasing problem. You might own enough beds but have too many waiting for pickup, too little cleaning capacity, or no vehicle available for an after-hours delivery. Before adding inventory, trace where the bottleneck occurs. Capital is most useful when it removes that constraint.
Your ownership model matters just as much. Some hospices manage bedside equipment themselves; others use a third-party durable medical equipment supplier. If your supplier provides beds and respiratory equipment, your own capital needs may center on communications hardware, vehicles, storage, or backup systems instead.
Mulah approaches the funding conversation around that operating picture: what you're buying, why it's needed, and how you'll pay for it without squeezing patient services. Equipment eligibility, pricing, and available structures are subject to the business, asset, vendor, and underwriting review. An application doesn't guarantee approval or particular terms.
Referral growth can justify additional inventory, but a referral forecast isn't the same as a deployed census. Use admission history, average equipment turnaround, and the geography you serve to estimate demand. Keep temporary surges distinct from sustained growth when setting the purchase quantity.
A practical inventory report separates deployed units, units awaiting pickup, units in cleaning or repair, and units ready for assignment. Within each group, note location and equipment condition. This makes shortages easier to diagnose and gives a financing request a stronger basis than a single fleet total.
Avoid sizing the entire purchase around your busiest possible month. A staged order may preserve cash while letting you add units as demand develops. Check vendor availability and delivery costs first, though: smaller orders aren't necessarily cheaper if repeated freight charges or long lead times create new problems.
Small business loans aren't interchangeable, and some arrangements below aren't conventional loans at all. Use this table to narrow the discussion, not as a promise that every product will be available for your hospice.
| Option | Often considered for | How to think about it |
|---|---|---|
| Term Loans | A defined expansion, replacement program, or other project with a known cost. | A lump sum repaid over an agreed term. Check total repayment, payment frequency, security requirements, and prepayment provisions. |
| Working Capital | Short-term operating needs supported by a credible cash-flow plan. | Funding for expenses such as payroll, rent, and vendor bills. Repayment schedules and costs vary by product. |
| Business Line of Credit | Recurring timing gaps or uneven expenses rather than a permanent cash shortage. | Draw against an approved limit, with borrowing costs and repayment rules set by the agreement. Access may be subject to ongoing conditions. |
| Equipment Financing or Leasing | Identifiable assets with vendor documentation and a clear business use. | A purchase-financing or leasing arrangement tied to equipment. Ownership, service coverage, and end-of-term obligations follow the contract. |
| SBA Financing | Eligible businesses seeking an eligible longer-term business investment. | Loans made by participating lenders with an SBA guarantee. Program rules and lender underwriting apply; documentation can be substantial. |
| Revenue-Based Financing | Businesses considering funding assessed partly on revenue and cash-flow history. | Some agreements purchase future receivables rather than make a conventional loan. Understand collection methods, total cost, and any reconciliation provisions. |
Financing a purchase may suit beds, lifts, and other assets you expect to maintain for years. Ownership gives you continuing use after the financing is repaid, subject to the agreement. It also leaves your business responsible for service, storage, eventual replacement, and disposal.
Leasing deserves a closer look when refresh cycles or return options matter. Tablets, dispatch hardware, and software-linked devices may become outdated sooner than mechanical equipment. But a lease only provides the flexibility written into it. Look closely at renewal language, buyout amounts, return condition, and shipping costs.
Run both choices over the period you realistically expect to use the asset. Include deposits, scheduled payments, service, insurance, and the final purchase or return cost. Don't assume a tax deduction makes the more expensive option better; tax and accounting treatment requires advice specific to your business.
A delivery van, ramp, cart, or warehouse lift may remove a more serious constraint than another batch of beds. Walk through a busy delivery day with your team. Where do units wait? Which tasks require extra handling? The answer should shape the asset list.
Cleaning stations, drying equipment, shelving, tracking hardware, and charging infrastructure can be necessary parts of a usable fleet. Obtain separate quotes for these items so their cost and eligibility are clear. Warehouse changes also need to fit your cleaning procedures, manufacturer instructions, and workplace requirements.
Keep clinical and infection-control decisions with qualified staff. Financing doesn't establish that equipment is appropriate for a patient or care setting. Medicare's hospice care coverage information provides useful context on medical equipment and supplies, but it doesn't replace your clinical policies or supplier agreements.
An acquisition or branch launch may involve equipment, integration work, and operating cash. Eligible broader-purpose funding may be worth discussing alongside asset financing. SBA loan options are one possible route for qualifying businesses; the SBA's official 7(a) guidance explains program uses and requirements.
For reimbursement-related cash gaps, accounts-receivable financing requires particular care. Healthcare receivables can involve payer rules, assignment restrictions, disputes, and recoupment exposure. Don't assume submitted claims are eligible collateral or that an advance transfers collection risk away from your business.
If you're considering revenue-based financing, understand the actual agreement rather than relying on the product name. Determine how collections affect your bank balance and how any adjustment process works. A short repayment pattern can be a poor match for equipment you'll use for years.
There isn't one universal qualification threshold. These are the business questions you should be ready to answer with records rather than optimistic projections.
Explain how long you've operated and whether this is an existing hospice, a new branch, or a startup. A new entity shouldn't be presented as having its owner's operating history.
Show how revenue turns into cash in your bank account. Explain unusual deposits, payment delays, or recent changes in payer mix that affect the picture.
List what you already owe, including equipment agreements, credit lines, and other financing. Existing liens or frequent withdrawals can affect both eligibility and affordability.
Provide model details, age, condition, warranty information, and vendor credentials. Used or specialized equipment may need additional documentation and isn't automatically eligible.
Tie quantities to replacement needs, census history, or a supported expansion plan. Explain where equipment will be stored and who will maintain it.
Show how you'll handle a lower-census period, delayed reimbursement, or an unexpected repair. Available cash after funding matters as much as the amount requested.
Requirements vary by transaction, but this working list will make the first conversation more productive. Send sensitive records through the designated secure process.
These categories keep a request concrete. Include only assets your business will own or lease under the proposed agreement, with supporting costs shown separately.
Electric hospital beds, controls, pressure-redistribution mattresses, overlays, and positioning accessories. Specify complete setups so missing components don't create unexpected spending after delivery.
Patient lifts, slings, wheelchairs, transport chairs, walkers, and commodes. Match quantities to actual use and include maintenance responsibilities for equipment with moving parts.
Oxygen concentrators, approved accessories, suction machines, nebulizer equipment, and provider-owned infusion-related equipment where appropriate. Clinical suitability and supplier responsibilities come before the financing decision.
Commercial vehicles, ramps, carts, and appropriate upfitting. Use the delivery schedule to justify capacity, and budget separately for drivers, insurance, fuel, and ongoing service.
Racking, cleaning and drying equipment, labeling systems, and inventory-tracking hardware. These purchases should support a documented workflow rather than simply add storage space.
Tablets, laptops, secure networking hardware, dispatch tools, and suitable backup power. Separate equipment purchases from recurring subscriptions, and account for replacement cycles.
These are planning situations, not customer results. Each calls for a different purchase list and a different test of affordability.
Measure how much growth has persisted before ordering a full expansion package. If ready inventory is consistently low despite efficient turnaround, added beds or mobility equipment may be justified. If units are stalled in cleaning, address that bottleneck first.
Budget for local storage and transport as well as bedside assets. Stage purchases around staffing, licensing, and realistic referral development so equipment payments don't begin far ahead of usable capacity.
Rank units by repair history, downtime, and parts availability. Replacing the most troublesome assets first can reduce disruption without committing to an all-at-once purchase.
Verify ownership and existing liens before treating acquired equipment as available capacity. Standardization may require replacement units, shared tracking hardware, or warehouse consolidation. Keep those costs consistent with the approved acquisition plan.
Concentrate on assets outside the supplier agreement. Vehicles, internal technology, and communications systems may still require capital. Check that planned purchases don't duplicate contracted services or shift maintenance responsibilities unintentionally.
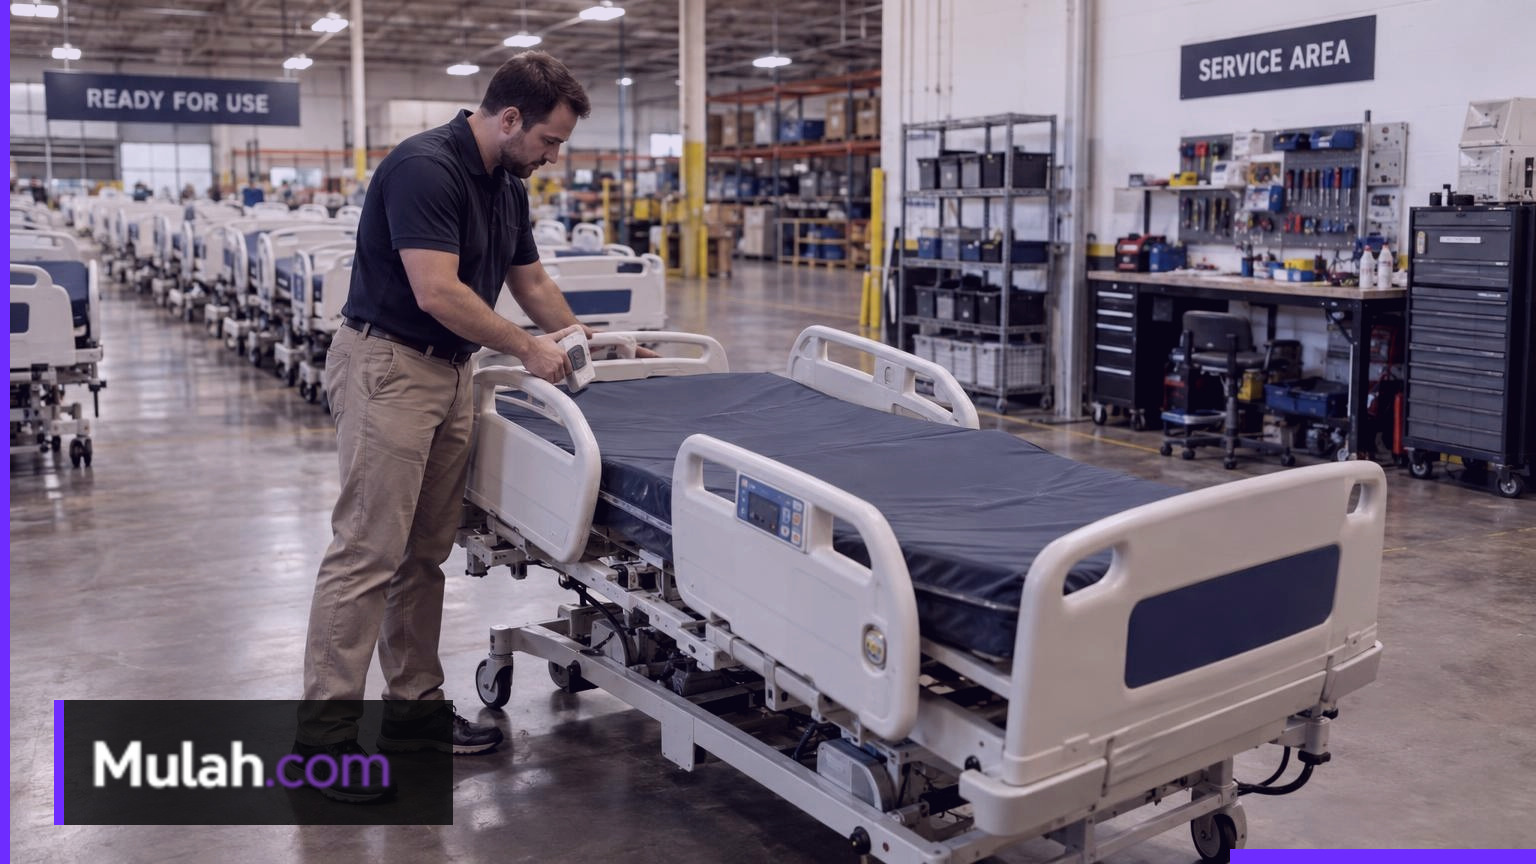
A branch opening can produce one long spending list: beds, warehouse rent, delivery vans, staff training, insurance deposits, and payroll. Those costs support the same project, but they aren't all equipment. Put quoted assets in one budget and the cash needed to run the branch in another.
Freight, installation, required accessories, and vehicle upfitting may be eligible parts of an equipment transaction. Training, rent, and wages often require another funding structure. Keep those amounts visible rather than adding unrelated expenses to a vendor invoice.
This separation also exposes the real size of the commitment. A vehicle payment is only part of its cost; insurance, fuel, maintenance, and driver time continue throughout ownership. Your forecast needs both the financing payment and the expenses required to keep the asset useful.
The number on your inventory report can overstate usable capacity. Track each stage before deciding how many additional units to finance.
List what a normal admission requires, including accessories that are easy to overlook. A bed without the right mattress, controls, or delivery arrangement isn't a complete setup. Separate standard packages from less frequently requested specialty equipment.
Service-area mileage, stairs, building access, and two-person handling can limit daily deliveries. More inventory won't solve a shortage of drivers or an overloaded route. Include the transport capacity needed to place equipment safely and on schedule.
Patients may need replacement accessories or a substitute unit during a repair. Your reserve should reflect actual service calls and maintenance history, not an assumption that every financed asset will remain continuously available.
Returned units need to be processed under your infection-control procedures before reassignment. Count equipment awaiting pickup separately from equipment being cleaned, inspected, or repaired. Those delays determine how much backup inventory you need.
Track repair spending, downtime, age, and parts availability by major asset class. Frequent repairs can justify replacement, but age alone isn't enough. A well-maintained unit may still be economical to keep, especially if financing a replacement would strain cash.
The right structure follows the use of the money. Don't put every cost into an equipment agreement just because equipment prompted the request.
Use an asset-focused structure for documented purchases such as beds, lifts, vehicles, and warehouse hardware. Ownership, service responsibilities, and end-of-term rights differ by agreement. The equipment financing and leasing guide explains the broader choices.
A defined project with a known budget may fit funding repaid over an agreed schedule. Make sure the financed improvements will remain useful through that period. See term loan options for projects extending beyond a single equipment invoice.
Payroll, fuel, rent, and reimbursement gaps belong in the operating forecast. A working capital loan addresses those needs differently from an equipment purchase. Borrowing should bridge a credible timing gap, not conceal recurring losses.
A reusable credit line may suit uneven, short-term needs when you can repay draws as cash comes in. It isn't a substitute for long-term asset planning. Check draw charges, renewal provisions, and repayment rules in the business line of credit guide.
Related Mulah resources include working capital funding, business lines of credit, equipment financing and leasing, term funding, SBA loans, revenue-based financing, startup funding, accounts receivable financing, and the business funding calculator.
An affordable-looking payment can hide an expensive commitment. Read the full agreement through these three practical lenses.
Put the proposed payment alongside payroll, pharmacy and DME bills, rent, taxes, and what you already owe. Account for payment frequency. A daily or weekly withdrawal affects your bank balance differently from a monthly payment.
Find out who handles preventive maintenance, emergency repairs, recalls, and replacement equipment. A lease doesn't automatically include service. If repairs remain your responsibility, budget for them rather than treating the scheduled payment as the full cost.
Read prepayment terms, purchase options, renewal provisions, return deadlines, and restoration requirements. Also check collateral and personal guarantees. Ask your legal, tax, and accounting advisers how the proposed contract affects your business before signing.
The amount that looks attractive on an offer is not always the amount that makes sense to take. Tie the request to a real expense, a realistic payoff period, and the cash the business can still live on if a customer pays late or a strong month comes in softer than expected.
You don't need a polished presentation. Mulah's starting point is a clear explanation of what you're buying, what it changes for your business, and how much cash needs to remain available. A bank may also be a strong option if you have an established relationship and time for its process; judge actual offers by cost and contract terms, not assumptions about either channel.
Use the business funding calculator to test payment scenarios, not to treat an estimate as a quote. Then check your funding options, or use the full application when your records and vendor quotes are ready.
A concise, well-supported request is more useful than a large collection of unexplained files. Give the funding provider a clear path from the equipment list to the business need.
State what you're buying, the vendor, the location, and when the equipment will enter service. Explain whether the project replaces worn units, adds capacity, or supports a new territory.
Provide requested business records and a forecast that includes the new payment. Explain material fluctuations in deposits, census, or expenses rather than leaving the reviewer to guess.
Match approved amounts to current quotes. Resolve differences in delivery charges, deposits, service coverage, and payment commencement before committing to the vendor or signing financing documents.
Provide the business and financial information needed for a funding review.
Start with a shorter path when you want to discuss the business need before completing the full application.
Review official SBA information about federal small-business loan programs and lender participation.
Official guidance on financial management, cash flow, bookkeeping, and business planning.
Use the official source for current program, regulatory, or business guidance related to this topic.
Use the official source for current program, regulatory, or business guidance related to this topic.
Potential purchases include beds, pressure-relief surfaces, lifts, wheelchairs, certain respiratory-support equipment, commercial vehicles, warehouse systems, and business technology. Submit an itemized list with intended use and vendor details. A clinical item being necessary doesn't automatically make it eligible for financing.
A documented multi-vendor purchase can be considered. Keep each quote separate and show delivery dates, deposits, and the total project cost. Find out how vendors will be paid and whether staggered deliveries affect when your payments begin.
Not necessarily. A lower scheduled payment can come with a longer commitment, a purchase option, or return costs. Calculate the full cost over your expected use period, including maintenance and the agreement's ending. Then consider how much ownership or refresh flexibility is worth to your business.
Only if the contract says so. Some leases include service provisions; others leave maintenance entirely with you. Get a written explanation of response times, replacement equipment, exclusions, and who handles manufacturer recalls.
Used equipment may be considered, but age, condition, useful life, vendor documentation, and service support matter. Obtain inspection and maintenance records where available. A low purchase price can be misleading if parts are difficult to obtain or refurbishment is required.
Those assets can be part of an equipment request when they support your business and meet product requirements. Include vehicle specifications, upfitting, racking, handling equipment, and installation costs separately so the full project is understandable.
You can investigate startup business funding, but a new hospice has a different underwriting picture from an established provider. Be prepared to discuss your licensing stage, ownership experience, available cash, business plan, and projected spending before revenue begins.
Usually, duplication needs a specific justification. Read the supplier agreement first, including backup coverage, service standards, and termination terms. Owning an additional fleet brings storage, cleaning, maintenance, and tracking costs that aren't visible in the purchase price.
Disclose them as separate operating needs. They generally don't belong on an equipment invoice. A broader funding package might address both categories, but the agreement should clearly state what the money can be used for and how each part will be repaid.
Build a monthly forecast using normal collections and a lower-census case. Include current debt, payroll, vendor bills, repairs, and the new asset's running costs. If the payment only works under uninterrupted growth, reduce the purchase or reconsider the timing.
Expect requests for ownership details, bank activity, revenue records, existing financing, and vendor quotes. Financial statements or tax returns may also be required. Keep the legal business name consistent across documents and explain material changes rather than submitting conflicting figures.
Possibly, but healthcare receivables require careful evaluation. Payer restrictions, claim disputes, recoupments, and assignment rules can affect eligibility. Get advice on your contracts and legal obligations before pledging receivables or accepting an advance against expected collections.
It can. The equipment often plays a role in securing the transaction, and other collateral or a personal guarantee may be requested. Read the security provisions closely, including whether they reach beyond the financed assets.
Match the agreement to your quote and check total payments, fees, payment commencement, service obligations, insurance, guarantees, and end-of-term terms. Resolve what happens if delivery is late or equipment arrives damaged. Keep enough cash outside the purchase to operate through ordinary setbacks.
Start with the need, the amount, and the timing. Mulah can help you review possible business funding options before you decide whether to move forward.
Call 877-816-8524