Collected Revenue
Bank deposits and financial statements show the scale and consistency of your receipts. Explain unusual deposits, transfers, or one-time projects so they aren't mistaken for recurring revenue.
Your firm's biggest expense may arrive weeks before a client pays an invoice. Professional Services Business Funding can bridge that gap or support a planned investment, but the payment schedule matters as much as the amount. Mulah helps you understand small business loans and other funding structures so you can judge what fits your cash flow, what it costs, and when borrowing makes sense.
Consulting practices, law firms, accounting businesses, and other professional firms often pay for labor before they collect for it. Monthly billing, client approval procedures, and disputed invoices can leave an otherwise profitable business short of cash. The useful question isn't simply how much funding is available. It's how much you need until collections catch up.
Expansion creates a different problem. Hiring an associate or adding a service line means paying today for revenue that may take months to develop. That calls for a funding plan built around hiring costs, realistic utilization, and the time required to turn completed work into collected fees.
Mulah's role is to put funding choices in that operating context. Availability, terms, and timing vary by provider, product, and your firm's finances. Treat any offer as a proposal to evaluate, not a reason to borrow the maximum available.
A professional firm can have modest equipment needs and still require substantial working capital. The main investment is often people: salaries, recruitment, training, and the time spent building client relationships. Those costs arrive on a schedule even when client receipts do not.
Your revenue model changes the financing picture. Monthly retainers may support a steadier forecast than project milestones. Contingent fees are less predictable still. A provider will want to understand not just annual revenue, but how reliably that revenue becomes available cash.
Owner distributions deserve attention, too. A practice can appear comfortable before distributions and tight afterward. Include reasonable owner compensation in your forecast, then decide which discretionary withdrawals could pause if collections slow. Borrowing to maintain distributions can leave the firm carrying debt without improving its earning power.
Small business loans are one part of the market. Credit lines, equipment leases, and revenue-based arrangements work differently. This comparison explains the trade-offs; it doesn't mean every product is available to every firm or through every provider.
| Option | Often considered for | How to think about it |
|---|---|---|
| Term Loans or Term Funding | A defined investment, such as an office build-out or a budgeted expansion. | A lump sum repaid over a stated period. Check payment frequency, interest or fees, security requirements, and early-payoff terms. |
| Working Capital Funding | A temporary operating gap with a credible source of repayment. | Funding for current expenses, often over a shorter period. Working capital describes the use; the underlying agreement determines the cost and payment obligations. |
| Business Line of Credit | Recurring fluctuations in collections or expenses. | Draw as needed within an approved limit. Interest and fees follow the agreement, and continued access can be subject to renewal or reassessment. |
| Equipment Financing or Leasing | Eligible computers, servers, office systems, or other business equipment. | Financing is tied to specific assets. Ownership, end-of-term choices, down payments, and maintenance responsibilities differ between loans and leases. |
| SBA Loans | Eligible firms seeking longer-term financing for qualifying business purposes. | Participating lenders make loans supported by an SBA guarantee. Underwriting, documentation, guarantees, and collateral requirements follow the program and lender. |
| Revenue-Based Financing | Firms whose revenue pattern and margins can support the proposed collection method. | Payments may be linked to revenue or collected through scheduled remittances under the contract. Some arrangements are purchases of future receivables rather than conventional loans. |
A credit line is useful when payroll falls before a predictable collection date. You draw for the shortfall, collect client payments, and reduce the balance. That pattern preserves access for the next cycle instead of financing the same expense indefinitely.
Watch the balance over several billing cycles. If it never falls, the issue may be inadequate margins, growing receivables, or an expansion that needs longer-term capital. Repeated draws can hide those problems until the line is nearly exhausted.
Check draw fees, unused-line charges, renewal conditions, and how each draw is repaid. Some products described as credit lines amortize individual draws over short periods. The label alone won't tell you how much cash will leave your account next month.
For technology purchases, equipment financing and leasing can tie the funding to an asset. Check whether installation, software, training, and ongoing subscriptions are included. A hardware agreement may leave much of the implementation bill unfunded.
For a broader expansion, SBA financing may be worth considering when the firm and intended use qualify. It generally requires more documentation and planning than a simple short-term funding request. The SBA guarantee supports the lender; your business remains responsible for repayment.
The SBA's 7(a) loan program guidance explains eligible uses and basic program requirements. For any longer-term commitment, test whether the investment should still produce value near the end of the repayment period.
Invoice financing is most relevant when you have completed the work and issued eligible business invoices. Providers may examine the client's ability to pay, invoice disputes, aging, and concentration. Find out who contacts your clients and where payments must be sent.
Revenue-based financing needs a different reading. Determine how remittances are calculated, whether adjustments are available when revenue changes, and what you must do to request them. Don't assume a revenue-linked label means withdrawals automatically decline during a slow month.
Legal and other regulated practices should also consider confidentiality, engagement terms, and restrictions affecting fees or assignments. Client trust funds and retainers aren't necessarily money the firm can spend. Keep them separate from the operating cash available for financing payments.
A useful application explains how your firm earns money and how it will repay the proposed funding. These six areas usually tell more than a headline revenue figure.
Bank deposits and financial statements show the scale and consistency of your receipts. Explain unusual deposits, transfers, or one-time projects so they aren't mistaken for recurring revenue.
An established practice has a payment history to assess. A new firm needs a credible budget and evidence supporting its revenue expectations; startup options are generally narrower.
Credit history, late payments, public records, and current borrowing can affect terms. Know whether the application involves a personal credit inquiry and a personal guarantee.
Heavy reliance on one client or a few contingent matters can increase uncertainty. Bring contracts, billing schedules, and a clear explanation of how revenue is distributed.
Show what remains after payroll, rent, taxes, and current debt payments. Gross revenue doesn't establish what your business can afford to repay.
Providers may verify ownership, entity records, licenses, and authorized signers. Professional licensing and firm-ownership rules remain relevant even when the financing itself is general business funding.
Requirements differ, but assembling these records early reduces avoidable back-and-forth. Keep financial statements current and make sure the figures reconcile with your bank activity.
The strongest funding requests connect an expense to a practical business outcome. Put a dollar amount and a realistic timetable behind the intended use.
Bridge payroll ahead of credible client receipts. Include employer taxes and benefits, not just net pay, when calculating the amount.
Budget recruiting, onboarding, and the period before the new hire reaches expected utilization. Revenue from a full calendar won't arrive on the employee's first day.
Account for data migration, security setup, and staff training alongside hardware. The transition period can create costs that a vendor's equipment quote doesn't capture.
Include deposits, construction or fit-out expenses, and moving disruption. Make sure projected demand supports the additional fixed overhead.
Training and marketing can support expansion, but results are uncertain. Use conservative revenue assumptions rather than treating every lead as a future client.
Temporary staff or contractors can support a busy filing or reporting season. Tie the funding period to when fees are actually collected, not when work ends.
These are decision examples, not customer results. Each highlights a different reason to borrow, adjust the request, or wait.
If approved invoices consistently clear after payroll, a credit line may fit the timing gap. First tighten billing and collection routines. Borrowing less after those fixes is better than financing preventable delays.
Price the extra labor through the first collection date and check the client's cancellation rights. If repayment relies entirely on one milestone, retain a cushion for approval delays or reduced scope.
Temporary staffing costs may precede collections by several weeks. Use prior seasons to estimate the peak cash shortfall, while allowing for changes in fees, client mix, and payment behavior.
A startup request rests heavily on owner finances, experience, and a defensible budget. Read about startup business funding, but don't plan around the same choices available to an established firm.
Check overdue receivables, write-offs, project overruns, and owner withdrawals before adding debt. Growth can require working capital, but financing won't repair work that costs more to deliver than you collect.
A temporary gap has a credible ending: an approved invoice is due, a seasonal billing cycle closes, or a contracted project reaches a payment milestone. Financing can be reasonable when you know which receipts will repay it and have room for a delay.
A persistent shortfall needs a different response. If fees don't cover staff time, overhead, and owner compensation, more debt adds another expense without fixing the underlying economics. Pricing, staffing, collections, or project scope may need attention first.
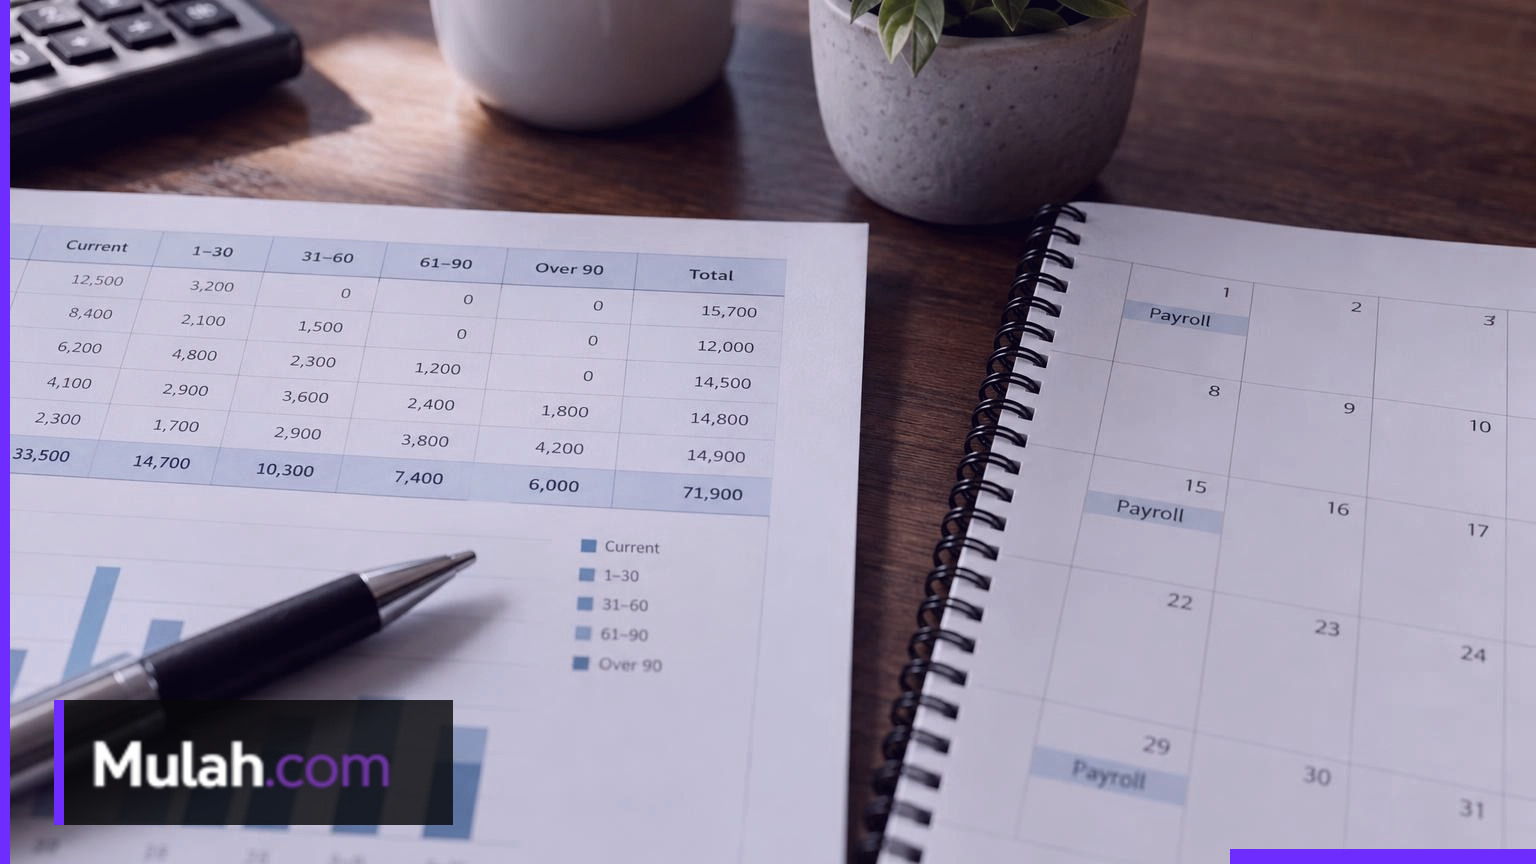
Put accounts receivable beside work in progress. Unbilled hours are not the same as approved invoices, and an invoice under dispute isn't equivalent to one scheduled for payment. That distinction matters both to your forecast and to a financing provider assessing the business.
The point where cash gets tied up should shape your funding choice. Map these stages before deciding how much to request.
A proposal pipeline is less dependable than an executed engagement. Note cancellation rights, deposit requirements, and any conditions that must be met before you can bill.
Include employee pay, contractor invoices, benefits, and project expenses incurred before the next billing date. A large assignment can consume cash even while it produces a healthy margin.
Missing purchase-order numbers, incomplete time entries, or late partner approval can postpone collection. Fixing those bottlenecks may reduce the amount you need to finance.
Build your forecast around when clients usually pay, not just the due dates printed on invoices. Keep disputed balances and unusually old receivables separate.
The receipt that repays financing may also need to cover next month's payroll. Don't count the same client payment twice when testing what you can afford.
Choose the job the money must do before choosing a product. These starting points narrow the search without treating every cash need as the same problem.
For a defined payroll or overhead gap, working capital funding provides cash for current expenses. Calculate the gap after expected collections, rather than borrowing an entire month's revenue.
A business line of credit lets you draw within an approved limit. It suits recurring timing gaps when you can pay down the balance between draws.
Term funding can spread the cost of a planned investment. Build a budget for the project and retain enough cash to handle a slower-than-expected ramp.
Accounts-receivable financing uses eligible invoices to support funding. Client credit quality, invoice age, contract restrictions, and collection arrangements all matter. Unbilled work generally requires a different assessment.
Related Mulah resources include working capital funding, business lines of credit, equipment financing and leasing, term funding, SBA loans, revenue-based financing, startup funding, accounts receivable financing, and the business funding calculator.
An affordable-looking payment can still be a poor fit. Look at the full commitment and how it behaves during a weak collection period.
Subtract withheld fees from the stated funding amount. Then total required payments and other charges. For loans, use APR when available to understand annualized borrowing cost; a factor rate is not an interest rate.
Monthly, weekly, and daily payments create different pressures. Place each withdrawal on your forecast, including weeks with payroll, estimated taxes, or few expected collections.
Read prepayment provisions, renewal terms, collateral requirements, and any personal guarantee. Paying early doesn't always reduce the cost by the amount you expect, especially with fixed-fee structures.
The amount that looks attractive on an offer is not always the amount that makes sense to take. Tie the request to a real expense, a realistic payoff period, and the cash the business can still live on if a customer pays late or a strong month comes in softer than expected.
Mulah can help you organize the request around the amount, purpose, and collection cycle. Bring the uncomfortable details as well as the strengths: an overdue major invoice, an existing advance, or a hiring plan that has slipped. Those facts matter to choosing a workable structure.
Use the business funding calculator for an initial payment illustration, then use the actual offer documents for your decision. A calculation isn't an approval or a complete statement of cost. Your cash forecast should include every required payment and fee.
Before applying, decide what the money must accomplish and how you'll repay it if collections arrive later than expected. A smaller, well-supported request is often more useful than an ambitious estimate with no cash-flow plan.
Write down the amount, intended use, and timing. Separate essential spending from optional spending, and account for cash already available to your firm.
Use the Mulah funding application and provide the requested records. Read the contact-consent language and privacy terms on the form before submitting.
Put the proposed payments into your forecast. Resolve questions about total cost, guarantees, liens, and early repayment before signing. Proceed only if the funding serves a clear purpose at a manageable cost.
Provide the business and financial information needed for a funding review.
Start with a shorter path when you want to discuss the business need before completing the full application.
Review official SBA information about federal small-business loan programs and lender participation.
Official guidance on financial management, cash flow, bookkeeping, and business planning.
Use the official source for current program, regulatory, or business guidance related to this topic.
Use the official source for current program, regulatory, or business guidance related to this topic.
Potential choices include term loans, working capital funding, credit lines, equipment financing, SBA loans, and receivables-based arrangements. The right starting point is your use of funds and collection pattern, not the largest advertised amount.
Working capital products commonly support payroll and other operating expenses, subject to the agreement. Include payroll taxes and benefits in the budget, and identify the receipts that will cover repayment.
Timing varies with the product, provider, application completeness, and verification required. Don't commit to a hire, purchase, or payroll transfer based on an expected approval date before funding is confirmed.
A credit line generally suits recurring timing gaps; a term loan generally suits a defined investment. The actual payment schedule and fees can change that judgment, so evaluate the specific agreement rather than the product name alone.
Some startup funding options exist, but a new firm has fewer records demonstrating repayment ability. Owner credit, relevant experience, available capital, and documented business prospects can become especially important.
There isn't one score requirement across all products and providers. Credit is considered alongside revenue, business history, current debt, and other factors. Avoid assuming an advertised minimum means approval.
Some financing requires owners to guarantee repayment. Read who must sign, what obligations the guarantee covers, and when personal liability applies. A business entity alone doesn't eliminate that exposure.
Eligible invoices may support accounts-receivable financing. Completed work, client credit quality, invoice aging, disputes, and assignment restrictions matter. A proposal or unbilled time entry is not the same as an eligible invoice.
Contingent-fee financing requires specialized assessment and isn't interchangeable with ordinary invoice financing. Ethics rules, fee arrangements, confidentiality, and the uncertainty of recovery need attention before you pledge anticipated proceeds.
Only funds your firm is entitled to use should enter the repayment forecast. Unearned retainers or money held in trust can be subject to restrictions. Follow the rules governing your profession and account arrangements.
Potentially, but product eligibility matters. Equipment financing may cover eligible hardware while subscriptions, implementation, and training require another structure. Budget the full project before choosing the financing.
Not always. Some agreements purchase future receivables rather than create a conventional loan. Read the contract's payment method, adjustment provisions, fees, and default terms instead of relying on the marketing label.
First total your current payments and check existing agreements for borrowing restrictions or liens. Additional funding should leave enough cash for ordinary expenses and a collection delay, not merely postpone a shortfall.
The SBA loan overview explains federal loan programs and connects to program-specific requirements. Use it alongside the lender's terms; SBA support doesn't remove your responsibility to repay.
Start with the need, the amount, and the timing. Mulah can help you review possible business funding options before you decide whether to move forward.
Call 877-816-8524