Business History
Explain how long you've operated and your relevant experience. Startup and acquisition requests need a clear account of who will run the business and how the launch or transition will be funded.
A new baler, vacuum truck, or water-treatment system can expand what your business earns. It can also tie up the cash you need to put it to work. Environmental equipment financing and leasing should account for both sides. If you're researching small business loans, look beyond the purchase price to installation, payment timing, and the reserves you'll need after delivery.
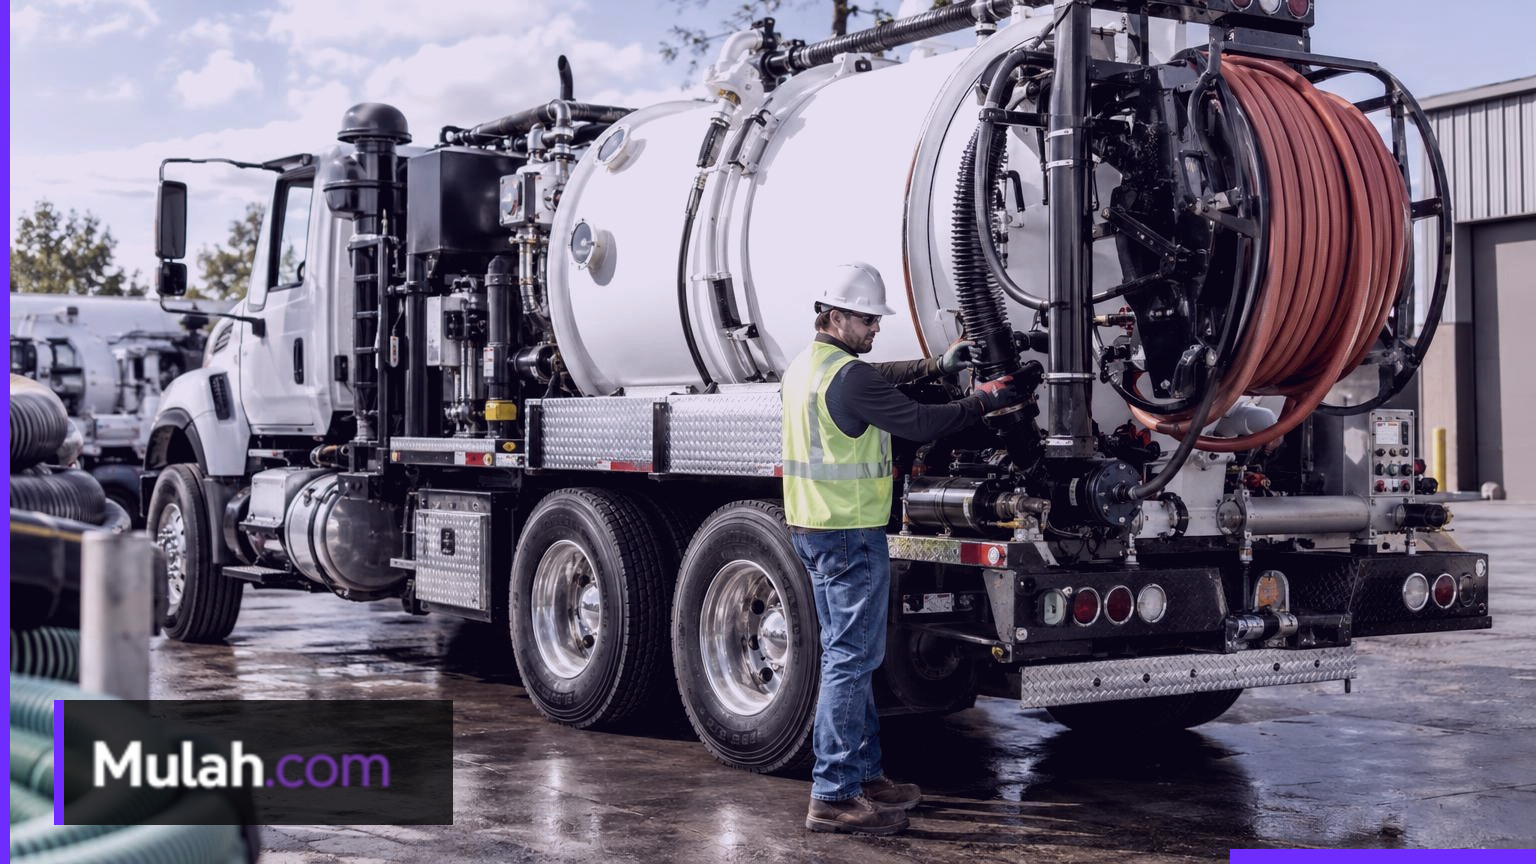
Environmental equipment rarely earns money on its own. A roll-off truck needs containers and a route. A treatment skid needs connections, testing, and an operator. Buying the main asset while leaving those costs unfunded can delay the revenue you were counting on.
Begin with the operating result: more tons processed, fewer rental days, reliable sampling, or the ability to fulfill a signed contract. Put a reasonable dollar value on that result, then deduct the labor and other expenses required to achieve it. Extra capacity isn't the same as extra profit.
Mulah approaches the funding request around that practical business need. The equipment quote matters, but so do your cash flow, delivery schedule, and the work the asset will support. A clear project budget gives the funding conversation a useful starting point.
Collection and recycling businesses often invest in connected systems: roll-off trucks, compactors, balers, conveyors, shredders, screens, magnets, optical sorters, and wash lines. One upgraded component won't necessarily increase output if another remains the bottleneck. Check material flow through the entire line before financing a higher-capacity machine.
Water and wastewater work brings a different set of assets, including pumps, tanks, filtration skids, dewatering systems, aeration equipment, centrifuges, and mobile treatment units. Field-service businesses may rely on vacuum trucks, jetters, hydro excavation units, containment equipment, generators, and trailers. Mobility, disposal arrangements, and setup time belong in the earnings estimate.
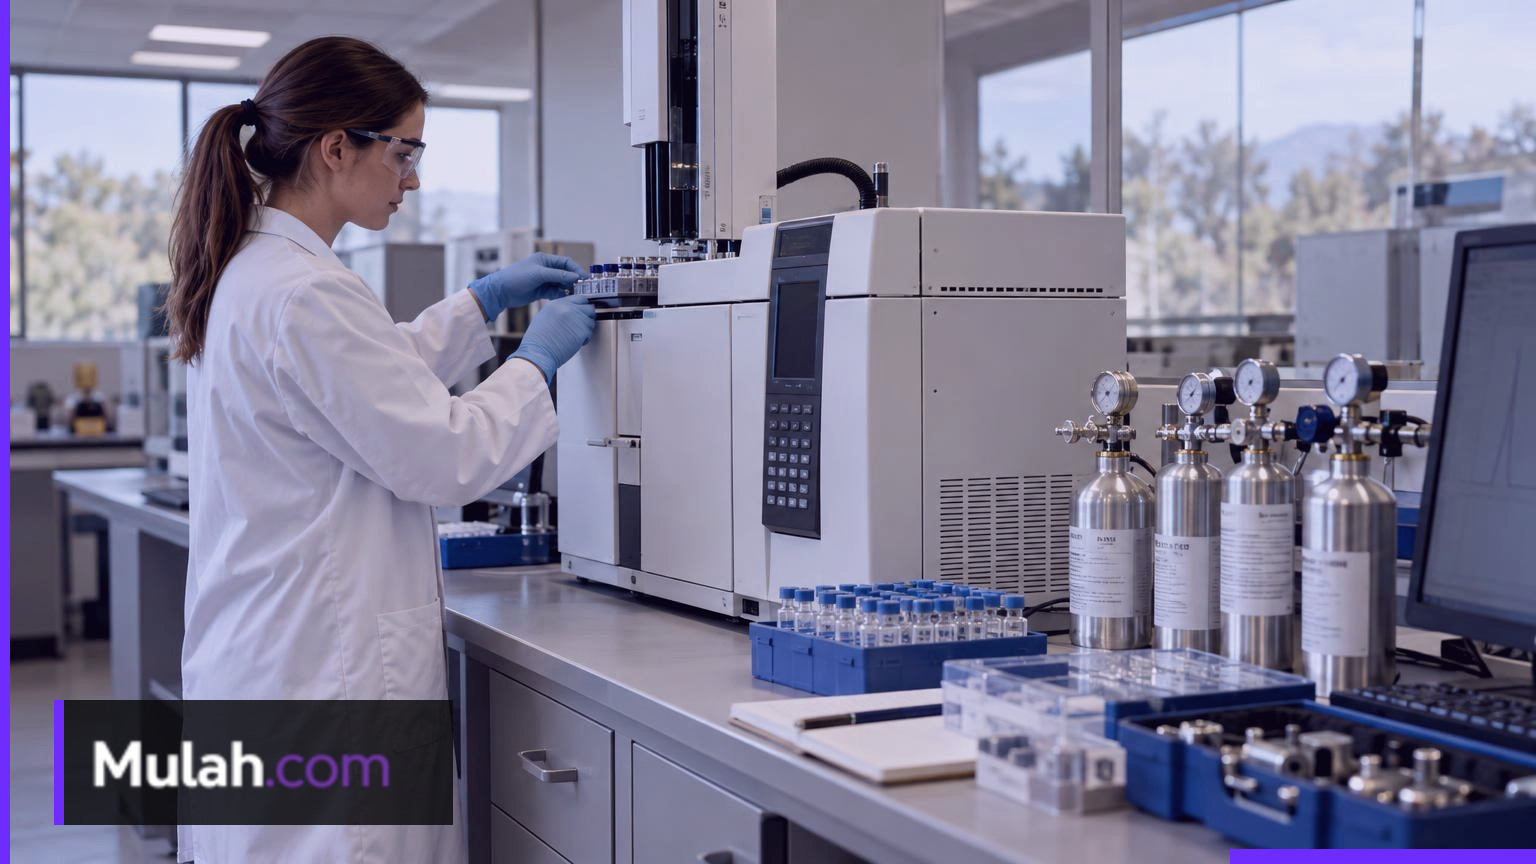
Testing laboratories and monitoring teams depend on analyzers, sampling instruments, spectrometers, data loggers, and calibration tools. Other investments include composting machinery, biochar systems, heat recovery, energy controls, used-oil processing, and battery-handling equipment. The business case should explain the asset's commercial use, not simply label it environmental.
When you shop for small business loans, you'll also encounter leases and other commercial funding agreements that aren't conventional loans. Choose by the expense you're funding, how cash comes into your business, and the total payment burden. These are product categories, not a promise that every option is available for your request.
| Option | Often considered for | How to think about it |
|---|---|---|
| Term Funding or Term Loans | A defined project with an upfront budget, such as equipment plus facility work. | A lump sum repaid over an agreed period. [Term funding](https://mulah.com/term-loan/) should be assessed for total cost, payment frequency, security, and prepayment provisions. |
| Working Capital | Payroll, fuel, disposal charges, consumables, and mobilization expenses. | Funding for day-to-day business needs rather than just an asset invoice. The repayment schedule should fit your customer collection cycle. |
| Business Line of Credit | Recurring parts purchases, uneven project spending, and temporary cash gaps. | A revolving facility with draws subject to its agreement. A [business line of credit](https://mulah.com/business-line-of-credit/) requires attention to draw fees, repayment rules, and renewal conditions. |
| Equipment Financing or Leasing | Identifiable machinery, vehicles, instruments, and attachments with a documented price. | [Equipment financing and leasing](https://mulah.com/equipment-financing-and-leasing/) ties the request to the asset. Ownership, collateral, and end-of-term obligations differ by contract. |
| SBA Financing or SBA Loans | Eligible businesses considering equipment or a broader qualifying investment. | Participating lenders make SBA-backed loans under program rules. [SBA financing](https://mulah.com/sba-loans-by-mulah/) involves lender underwriting and program-specific eligibility and documentation. |
| Revenue-Based Financing | Businesses evaluating funding against an existing revenue stream. | [Revenue-based financing](https://mulah.com/revenue-based-financing/) isn't an equipment lease. Examine how payments or remittances are calculated and what happens when sales change. |
Request itemized estimates for freight, taxes, applicable customs charges, rigging, foundations, electrical service, ventilation, plumbing, software, guarding, and commissioning. For mobile units, add body upfitting, hoses, tanks, attachments, telematics, registration, and any insurance increase. Mark exclusions clearly so they don't disappear between vendor and contractor quotes.
Facility work deserves particular attention. A separator might require conveyors and dust collection; a treatment system might require drainage and additional power. Assign responsibility for each connection and inspection. Otherwise, the machinery vendor and installation contractor can each assume the other included essential work.
Include training, initial consumables, and a reasonable contingency supported by the project's uncertainties. Then distinguish costs eligible under the proposed funding agreement from costs you'll pay separately. A complete budget isn't permission to finance every item under the same product.
Obtain the model, year, serial number when available, operating hours, service history, photographs, and warranty terms. For vehicles, include title information. With specialized machinery, arrange an independent inspection that addresses wear, corrosion, contamination, controls, and the ability to handle your intended materials.
Check the chassis and mounted systems separately on a vacuum or hydro excavation truck. A sound vacuum module doesn't cure a worn drivetrain. For laboratory instruments, investigate calibration history, software licensing, support, and the availability of sensors or other replacement components.
Price necessary refurbishment before committing. Transport, rebuilding, installation, and early downtime can erase a low purchase price. A private sale or unusual asset can also require more valuation work, so leave time for documentation rather than promising the seller an unsupported closing date.
Estimate incremental earnings using billable hours, processing volume, route density, avoided rentals, or reduced downtime. Deduct the associated wages, fuel, power, maintenance, insurance, disposal costs, and service contracts. Use incremental profit and available cash, not the full value of a customer contract.
Run a slower case with delayed commissioning, lower commodity prices, a repair, or a late contract renewal. Add the proposed payment to what you already owe. If covering it requires every customer to pay on time and every shift to run at capacity, the commitment is too tight.
The [Mulah Business Funding Calculator](https://mulah.com/business-funding-calculator/) is a planning tool, not a quote or approval. Use it beside your installed-cost budget and monthly cash forecast. Include your deposit and the reserve you want to retain, then replace estimates with actual offer terms before signing.
Your application should connect the equipment to a credible way of paying for it. Give a straightforward picture of your business, including weak spots that affect the plan.
Explain how long you've operated and your relevant experience. Startup and acquisition requests need a clear account of who will run the business and how the launch or transition will be funded.
Show how much your business brings in and when customers pay. Seasonality, concentrated customers, and large unpaid invoices affect how comfortably you can carry another payment.
List loans, leases, credit lines, and other funding commitments. Include payment frequency so several smaller deductions don't hide the true monthly cash burden.
Be prepared for business or owner credit review and questions about collateral or guarantees. Understand whose assets and obligations are involved before accepting the agreement.
Provide a detailed quote, condition information, and vendor contact. A readily valued asset and a documented sale are easier to assess than an incomplete description and an estimated price.
State what you can contribute without draining cash. A deposit isn't the whole commitment if installation, first-month expenses, and emergency repairs still need to be paid.
Gather these records before applying. Requirements vary, but an organized file reduces back-and-forth and exposes missing project costs early.
A strong request explains what changes after the money is spent. These common uses call for different budgets and evidence.
Use repair bills, downtime records, and lost productive hours to judge replacement. The oldest machine isn't automatically the first one to replace; prioritize the failure that disrupts profitable work.
Support a larger baler, additional sorting stage, or second treatment unit with documented demand. Check that labor, feedstock, downstream buyers, and the rest of the facility can support the increase.
Budget for required attachments, monitoring equipment, containment, trailers, and support vehicles. Read cancellation and payment terms before taking on a long-lived commitment for a short assignment.
Coordinate machinery with pads, drainage, ventilation, fire protection, and controls. The capital plan should fund a usable installation, not leave an expensive asset waiting for unfinished infrastructure.
Inspect inherited equipment before planning fleet standardization or expansion. Deferred maintenance, missing service records, and incompatible systems can change how much cash you need after the ownership transition.
Separate recurring repairs, consumables, payroll, and fuel from the equipment purchase. Use an appropriate operating-capital structure rather than assuming the equipment agreement will cover future expenses.
These are planning situations, not customer outcomes. Use the one closest to your project to challenge the numbers before taking on a payment.
Your old unit still needs repairs while the new one is being upfitted. Price temporary rental or repair costs and check when the new financing payments begin.
Higher recovery doesn't guarantee higher cash flow when commodity prices fall. Test the payment using weaker sale prices and the cost of storing or moving unsold material.
Count realistic paid tests, not theoretical instrument capacity. Include validation, calibration, software, and skilled staffing before deciding how many tests cover the monthly commitment.
A signed contract doesn't pay the first fuel or payroll bill. If eligible invoices are involved, [accounts-receivable financing](https://mulah.com/accounts-receivable-financing/) is a separate option to evaluate for collection timing, fees, and customer requirements.
With little operating history, the plan needs stronger support for demand, experience, and cash reserves. [Startup funding](https://mulah.com/startup-business-loans/) deserves its own assessment rather than assumptions based on an established business's options.
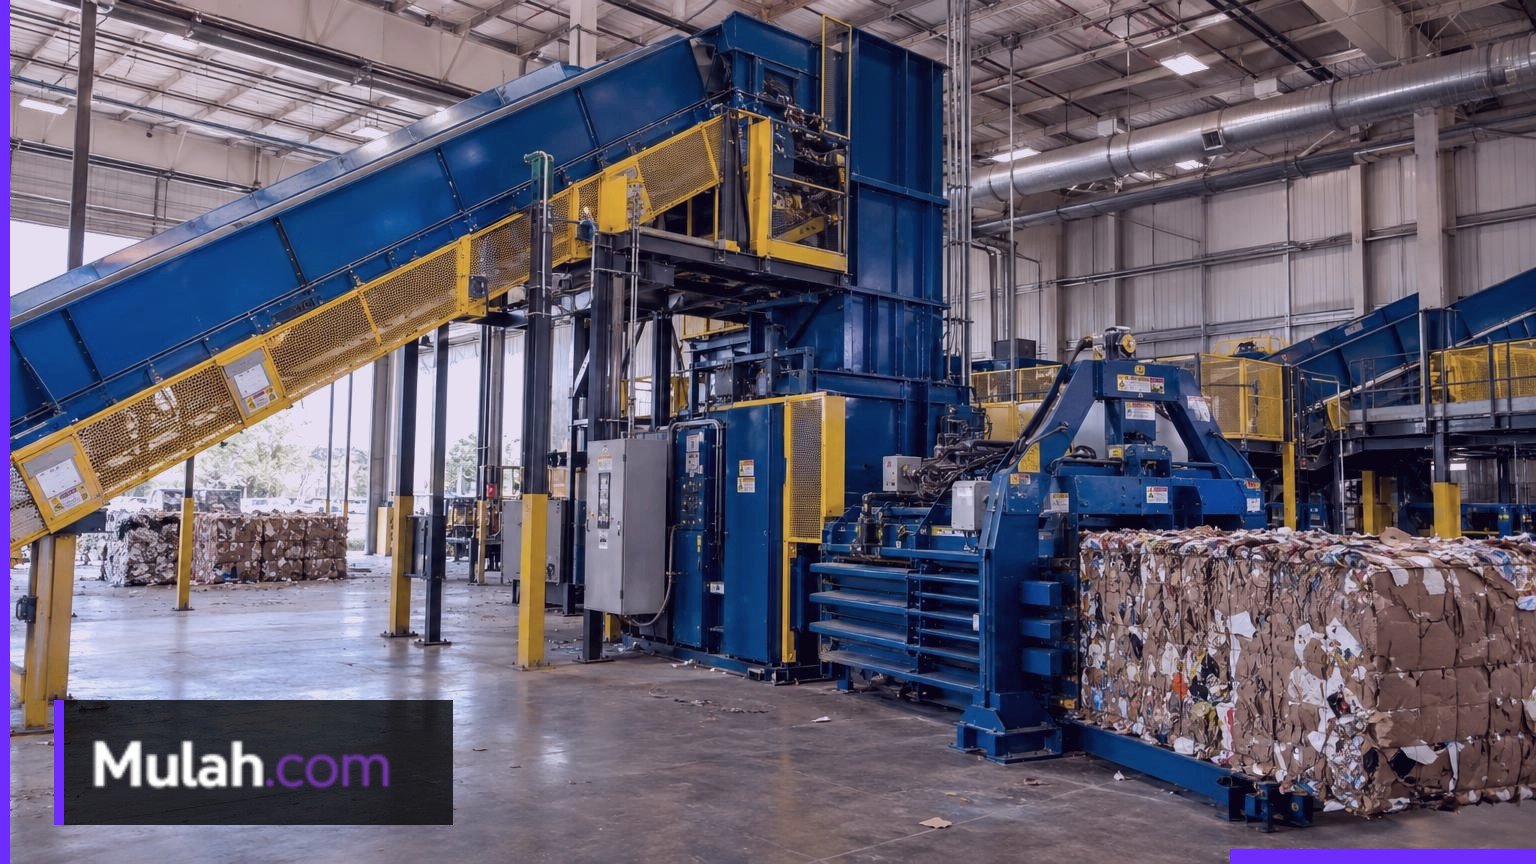
A truck or processing line is a long-term investment. Fuel, wages, testing supplies, and disposal charges are recurring expenses. Putting everything into one undifferentiated funding request makes it harder to judge what the equipment costs and what your business needs to keep running.
For example, a remediation contract might require a vacuum unit before mobilization, followed by several weeks of payroll before the customer pays. The asset purchase and the collection delay are different financing problems. They also carry different risks if the job slips.
Budget for both, but don't assume one agreement covers them. [Working-capital funding](https://mulah.com/working-capital-loans/) addresses operating needs, while an equipment arrangement centers on the asset. If you use separate products, calculate their combined payments before deciding what you can afford.
Delivery isn't the finish line. Map the dates when you must spend money against the date the equipment can begin producing billable work.
Custom machinery may require a deposit and progress payments before shipment. Get the schedule in writing and determine which payments you must cover yourself before financing proceeds become available.
Rigging, electrical work, plumbing, or vehicle upfitting can keep delivered equipment out of service. Allow cash and time for that gap rather than treating the delivery date as the first revenue date.
Testing, calibration, operator training, and controls integration take time. Establish what counts as acceptance under the purchase agreement and how deficiencies will be corrected.
A new line may run below its rated throughput while crews learn the process or material supply develops. Base early payment planning on a realistic ramp, not full utilization from day one.
Billing cycles, retainage, and customer payment terms can stretch the gap further. Leave enough cash to pay your suppliers and employees while completed work moves through the collection cycle.
The lowest advertised payment doesn't necessarily produce the lowest cost. Your expected holding period and the contract's final obligations matter just as much.
Ownership-oriented financing often fits durable equipment you expect to keep for years. Check the down payment, security interest, payment schedule, and any remaining balance at maturity. Avoid stretching payments beyond the asset's realistic productive life.
A lease can preserve upfront cash or support a planned replacement cycle. Read the purchase option, return conditions, usage restrictions, maintenance duties, and early-exit costs. Don't assume every lease lets you return the equipment without another obligation.
Cash removes a financing payment, but it also leaves your account immediately. It makes sense only if the remaining reserve can absorb ordinary bills, a repair, and a slower collection period without forcing expensive emergency borrowing.
Rental can bridge a delivery delay or serve a short assignment without a long ownership commitment. For recurring work, calculate rental, transport, and availability costs against buying. Temporary access becomes expensive when the need is effectively permanent.
Related Mulah resources include working capital funding, business lines of credit, equipment financing and leasing, term funding, SBA loans, revenue-based financing, startup funding, accounts receivable financing, and the business funding calculator.
A well-supported purchase answers three operating questions before you spend time on applications.
Capacity alone isn't enough. Material compatibility, pressure, payload, emissions controls, reach, and site access can determine whether the machine actually satisfies your contract.
Check service coverage, parts availability, consumables, and operator skills. A specialized asset with no practical repair support can become an expensive bottleneck.
Know what happens if demand falls or delivery slips. Rental access, a second supplier, or a usable resale market gives you more room than a single-purpose machine with no substitute.
The amount that looks attractive on an offer is not always the amount that makes sense to take. Tie the request to a real expense, a realistic payoff period, and the cash the business can still live on if a customer pays late or a strong month comes in softer than expected.
Mulah gives you a place to present the equipment need alongside the business behind it. That includes the installed cost, what you're trying to accomplish, and any separate working-capital gap. The goal is a useful funding discussion, not simply the largest amount you could request.
Before proceeding, settle the questions that financing can't answer for you: whether the asset fits the job, whether demand supports the investment, and how much cash must remain available. Then use the funding-options path or full application with a budget you can defend.
Turn the purchase plan into a request you can explain in a few clear sentences: what you're buying, why you need it, the complete cost, and how your business will carry the payment.
Separate the equipment price, installation budget, and operating reserve. Include trade-ins, deposits already paid, and any cash contribution. Note the vendor's deadlines without assuming financing will meet them.
Use the [funding-options request](https://mulah.com/get-fast-business-funding-from-mulah/) for an initial discussion, or the [full application](https://mulah.com/application/) when your information is ready. Keep quotes and supporting records consistent with the amount requested.
Check total repayment or lease cost, fees, payment frequency, collateral, guarantees, insurance, default provisions, and prepayment terms. Make sure the equipment description is correct and the agreement addresses deposits, delivery delays, substitutions, and lease-end obligations.
Provide the business and financial information needed for a funding review.
Start with a shorter path when you want to discuss the business need before completing the full application.
Review official SBA information about federal small-business loan programs and lender participation.
Official guidance on financial management, cash flow, bookkeeping, and business planning.
Use the official source for current program, regulatory, or business guidance related to this topic.
Use the official source for current program, regulatory, or business guidance related to this topic.
Common examples include collection vehicles, balers, sorting machinery, pumps, filtration systems, vacuum units, hydro excavation equipment, testing instruments, and remediation systems. Provide the specifications and intended commercial use so the request reflects the actual asset.
Some structures accommodate documented freight, installation, software, commissioning, or training; others focus on the equipment invoice. Get an itemized budget and a written explanation of which costs the offer covers. Keep separate cash available for exclusions.
Leasing can suit a replacement cycle or a smaller upfront commitment. Financing a purchase often fits a long holding period. The deciding factors are total cost, ownership goals, maintenance duties, and end-of-term obligations, not the product name.
Used assets can be considered, but condition, age, remaining life, value, and seller documentation matter. An inspection is especially worthwhile when the asset is specialized, expensive to move, or essential to fulfilling your contracts.
Base the reserve on your actual bills and collection cycle, not a universal percentage. Allow for payroll, fuel, taxes, maintenance, and a plausible delay before the new asset earns cash. Include what you already owe in that calculation.
A startup request needs a credible operating plan, relevant experience, a complete budget, and support for expected demand. Owner contributions, collateral, or guarantees can be important. Don't assume equipment alone will support the entire request.
SBA programs include eligible equipment uses. The official SBA 7(a) guidance explains program uses and eligibility, while participating lenders make lending decisions. Allow for the required documentation and determine whether the project fits the program before relying on it.
Those costs usually belong in an operating-capital budget rather than being assumed part of an equipment agreement. If you need both asset funding and working capital, evaluate the combined cost and payments so one commitment doesn't undermine the other.
Request an itemized quote, specifications, condition details, warranties, delivery terms, and a payment schedule. Used assets need supporting history and inspection information. Spell out installation responsibilities and exclusions so you know who is supplying each part of the project.
Financing doesn't establish regulatory suitability. Verify requirements for your materials, site, and work with appropriate technical and compliance professionals. OSHA's hazardous-waste resources are relevant to covered cleanup work, but requirements differ across environmental activities.
Read when payments begin, when funds go to the vendor, and what remedies exist for late delivery or failed acceptance. Budget for temporary equipment and extra labor where necessary. Don't rely on a verbal promise that payments will wait.
The agreement controls. Look for prepayment charges, minimum finance costs, or other provisions that affect the payoff amount. For a lease, early termination can work differently from paying off a loan. Obtain the calculation in writing.
Tax treatment varies with the transaction and your circumstances. Have your accountant assess depreciation, deductions, capitalization, and lease classification before choosing a structure for tax reasons. A marketing description isn't a substitute for transaction-specific advice.
Put the full cash commitments side by side: upfront contribution, scheduled payments, fees, and any final purchase or return costs. Then examine guarantees, security interests, insurance, and default terms. Choose an affordable structure under a conservative forecast, not merely the smallest periodic payment.
Start with the need, the amount, and the timing. Mulah can help you review possible business funding options before you decide whether to move forward.
Call 877-816-8524